Nvidia's earnings mark start of post-Jensen era

Add Axios as your preferred source to
see more of our stories on Google.
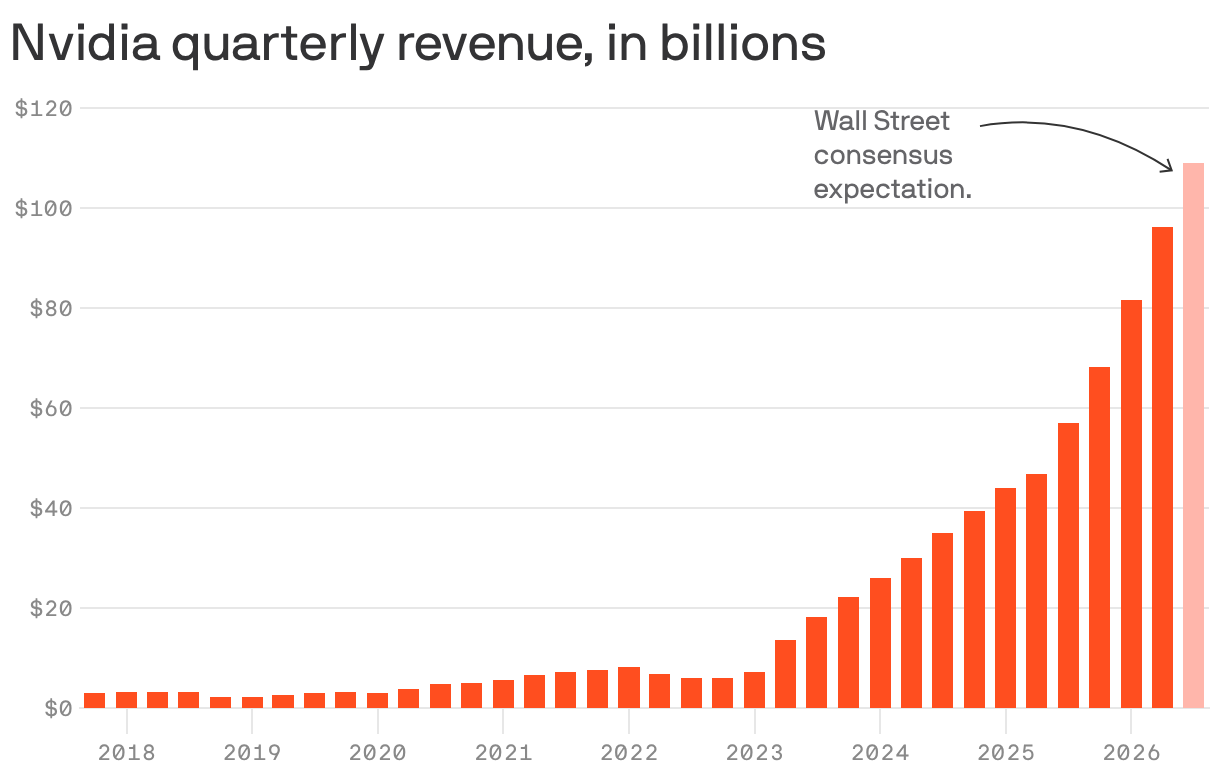
Nvidia's post-Jensen Huang era begins in earnest with the release of its third-quarter results after the close of trading Tuesday.
Why it matters: Investors and analysts will be reading tea leaves and listening for hints about near-term changes the company is making (or expecting the government to make) as a result of Huang's resignation last week and the circumstances that led to it.
The big picture: Besides selling the world's most sought-after AI processors, Nvidia is a giant source of financial backing to the AI ecosystem — buying equity, making co-investments and backstopping debt in companies ranging from neoclouds like CoreWeave to fiber-optic cable providers like Lumentum.
- Nvidia is also a major partner of the two AI labs at the heart of the boom, striking a deal to provide a backstop for an OpenAI data center in Ohio and planning to invest about $10 billion into Anthropic following its IPO later this week, according to its prospectus.
- Huang could make these unorthodox deals — some call them circular finance — because of his position as a co-founder and sole CEO of Nvidia.
- Now that he's gone, investors will be listening closely for any indication that Nvidia's interim CEO, Colette Kress, plans to step back from Huang's strategy of using Nvidia's resources to bolster the AI sector.
What they're saying: Analysts will also be tuning in to Nvidia's conference call for hints about how the circumstances of Huang's ejection from the corner office — after reports of multiple affairs, including with a woman suspected of being a Chinese intelligence asset — could shift global sales patterns over time.
- "Our biggest concern now is new scrutiny that may restrict some of its sales into certain geographies such as Singapore/Malaysia. In a worst case, we estimate this could cut up to ~10% out of revenue," wrote UBS analysts.
- "Greater scrutiny of NVDA Asia shipments that indirectly (via cloud) service China customers, or more conservative funding/product allocation to US emerging/neocloud customers could also impact market share," wrote analysts with BofA Securities.
- "While the findings of the independent probe by NVIDIA and Congressional scrutiny remain to be seen, one possible outcome could be enhanced export restrictions," wrote analysts at HSBC, in a note downgrading the stock to "hold" from "buy" last week, adding that "during the past six quarters, 11% of total revenue was from countries excluding the U.S. and Taiwan, which we believe could be the focus of restrictions."
By the numbers: Few expect anything other than another giant jump in sales and profits in the report itself. (If there's a significant miss, the already wobbly AI trade would likely get another clubbing.)
Zoom in: That said, we'll be watching data center sales, which are expected to nearly double to about $101.87 billion.
- Also, given the weakness in the market, Nvidia's guidance for overall revenue in the current quarter will be of interest. Wall Street analysts expect it to be $125.2 billion.
- The company offered full-year sales guidance for the first time ever last quarter, and any tweak to the approximately 70% Nvidia previously said it expected for fiscal year 2028 sales growth will be huge.
The bottom line: This will be a very delicate earnings report for the interim CEO and the rest of Nvidia's team to handle.
